The Merger Has a Price. The Name Doesn't.
A CPRS view on the one asset neither merger offer itemizes: a 118-year-old Black Wall Street name.
A merger vote that also decides a name.
A bank can be merged in an afternoon. A name that financed Black homeownership through the 1920s, reopened first after the 1933 bank holiday and outlived all but a handful of its peers took 118 years to build. Only one of those is on the ballot on October 20, and only one of them shows up in the merger arithmetic.
M&F Bancorp, holding company for Durham's Mechanics & Farmers Bank, agreed on July 22, 2026 to merge with Optus Financial of Columbia, South Carolina, in a deal valued at about $105 million. Under that agreement the bank takes the Optus name about two years after closing and headquarters moves to Columbia. Triad Business Bank of Greensboro has made a competing bid that would keep the Mechanics & Farmers name and the Durham headquarters. M&F's board has rejected every Triad proposal.
| Term | Optus Financial | Triad Business Bank |
|---|---|---|
| Status | Signed agreement, Jul 22 Agreed | Unsolicited; rejected by board Rejected |
| Per-share terms | $46.57 at closing, plus up to $6.73 contingent on repurchase of preferred shares within 12 months | $53.50 cash for up to 25% of shares, or 1.25 shares in the combined company |
| Name | Changes to Optus about 2 years after close | Mechanics & Farmers kept |
| Headquarters | Columbia, SC | Durham, NC |
| Structure | Single merged bank; largest Black-owned bank in the US | Two banks kept separate under one holding company |
The board found Triad's proposals "significantly undervalue M&F" and remains "fully committed to the merger with Optus." That judgment is the board's to make, and this record takes no position on it or on the vote. Both bidders are Black-led institutions with their own history; Optus traces itself to Victory Savings Bank, South Carolina's first Black-owned bank, founded in 1921.
The narrower question this record asks: if the name sunsets, what goes with it, and has anyone written it down? The public record does not let anyone isolate how much of the gap between the offers attaches to the name, the headquarters, the structure or closing risk. CPRS does not try to. It rates the name on its own.
What the name actually holds.
The North Carolina General Assembly chartered Mechanics and Farmers Bank on February 25, 1907. Seven founders raised $10,000, and the bank opened on August 1, 1908 inside the North Carolina Mutual and Provident building in Durham's Hayti district.
No large loans to a few profiteers, but rather conservative sums to needy farmers and laborers.Founding lending policy, as recorded · Baradaran (2017)
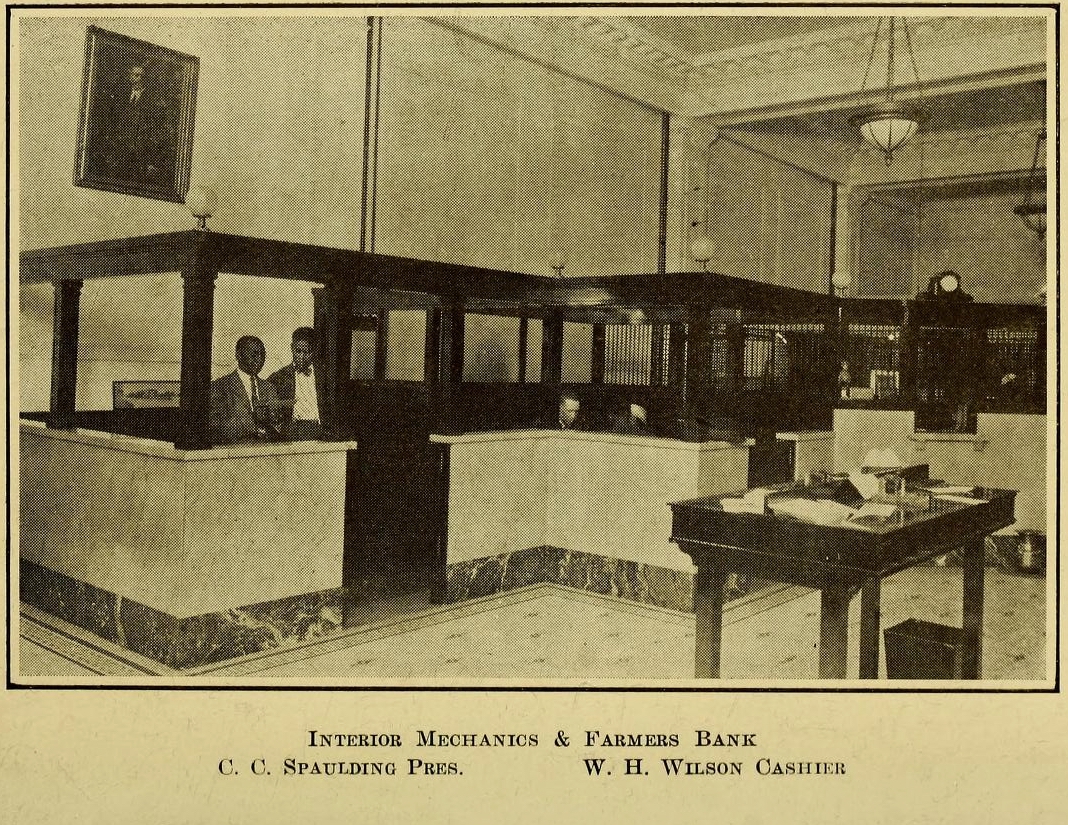
The name says who the bank was for. For CPRS purposes the property is not the charter, the deposits or the branches. It is the name as a carrier of lineage: what a Durham family means when they say their grandparents' first mortgage came from M&F.
- 1907
Chartered by the NC General Assembly; seven founders raise $10,000.
- 1908
Opens August 1 in the NC Mutual and Provident building, Hayti.
- 1921
Moves in December to West Parrish Street, the core of Durham's Black Wall Street.
- 1923
Raleigh branch opens January 1: the only Black-owned bank with a branch, and one of 119 US banks operating branches.
- 1920s
About $200,000 in loans secures Black ownership of more than 500 properties. The bank also finances a Durham synagogue.
- 1933
First NC bank to reopen after the federal bank holiday; one of eight Black-owned banks to survive the Depression.
- 1935
First NC lender to receive an FHA Certificate of Authority.
- 1952 to 1978
John H. Wheeler leads the bank as CEO, following C. C. Spaulding's presidency.
- 1999
M&F Bancorp forms as holding company; trades OTC as MFBP.
- 2016
First annual net loss.
- JUL 22, 2026
Optus merger announced, about $105M; name to change about two years after close.
- OCT 2026
Triad's bid to keep the name and Durham HQ becomes public. Vote, originally October 7, is delayed.
- OCT 20 · OCT 21
Shareholder vote (per Axios). Last day Triad's offer stands (per Triad).
Today the bank runs seven branches: two in Raleigh, two in Durham, and one each in Charlotte, Winston-Salem and Greensboro. It is the second-oldest Black-owned bank in the United States.
BCPV 63.00, carried by lineage.
| Dimension | Raw | Weight | Contribution |
|---|---|---|---|
| CISCultural Influence Score | 72 | ×0.30 | 21.60 |
| CCIConsumer Conversion Impact | 48 | ×0.25 | 12.00 |
| LIPLikeness & Identity Premium | 70 | ×0.20 | 14.00 |
| CUVCommercial Usage Value | 40 | ×0.15 | 6.00 |
| HLMHeritage & Lineage, 0 to 100 raw · lead dimension | 94 | ×0.10 | 9.40 |
| BCPV | Heritage-heavy fingerprint | 63.00 | |
CIS 72. The name is a fixed reference point in the Black Wall Street story, alongside NC Mutual, and the bidding contest is drawing regional and national coverage. Held in the low 70s because recognition is deep but concentrated: strongest in North Carolina, in Black business history and among HBCU and faith communities, not in mass-consumer awareness.
CCI 48. A bank name converts to deposits and loans, not cultural consumption, and nothing in the public record isolates how much customer acquisition the name itself drives. The bank recorded its first annual net loss in 2016, and its shares trade thinly over the counter. The name's pull is asserted far more often than it is measured.
LIP 70. The likeness here is institutional: the M&F mark, the full name and the founders it invokes, including Merrick, Shepard and Spaulding. Identity is strong and specific. Discounted because trademark registration status and archive custody are not verified in this pass.
CUV 40. Commercial usage runs through one channel, a seven-branch community bank. There is no licensing program, no heritage line and no structured use of the name beyond banking. This is the lowest dimension, and the one that falls toward zero on a sunset.
HLM 94. This is the property: 118 years of continuous operation under one name, a documented founding with named originators, Depression survival, firsts in North Carolina banking and a measurable community-ownership record in the 1920s lending. Held below 100 only because custody is institutional and the founding archive's location and condition are not confirmed.
HLM in the 90s inside a composite at 63
Heritage-heavy records typically show HLM in the 80s to low 90s inside a sub-63 composite. $MFBANK sits at the upper edge of that shape: the strongest lineage score over the weakest commercial-usage score. Tenure has outrun commercial use. The composite understates the property by design, which is why CPRS carries heritage a second time, once, as a multiplier at the monetary stage.
A modeled band of $2.6M to $5.3M.
| Step | Calculation | Result |
|---|---|---|
| BCPVFive-dimension composite | 21.60 + 12.00 + 14.00 + 6.00 + 9.40 | 63.00 |
| CDCCultural Demand Coefficient | 0.75 × 0.40 × 3.0 (financial services routed at 3.0, disclosed) | 0.90 |
| CPRS IndexBCPV × CDC | 63.00 × 0.90 | 56.70 |
| Base valueValue-unit method | 56.70 × $25,000 per index point | $1.42M |
| HLM multiplierApplied once, monetary stage | $1,417,500 × 2.8 | $3.97M |
| TCPMV band±34% at confidence 0.66 | $3.97M × 0.66 to $3.97M × 1.34 | $2.62M to $5.32M |
Tier placement. The full band sits inside Tier 4 (Heritage & Lineage, Landmark, $2M to $10M+), and the 2.8× HLM multiplier clears the 2.5× typical of Tier 4 records. The margin is stated plainly: the low end clears the Tier 4 floor by $0.62M. A confidence factor below about 0.50 would push the low end into Tier 3. The record is placed by the band, not rounded into the tier.
Why 2.8×, not 3.0×. The lineage is documented, continuous and community-anchored, which supports the top of the range. It is held back because the founding archive and trademark custody are not verified, and because the name's continuity is contested this week. If the archive is confirmed intact and held by the custodian, 3.0× would move the central value to about $4.25M.
The band rates the name as cultural property: the heritage identity a steward could register, protect and route value through. It is not an appraisal of the trademark, a share of either bid, or a view on the bank's enterprise value. Both offers address the name as a deal term. Neither records it as a property.
Where a registered name would route value.
A heritage name has more surface than a sign over a door: archival licensing, documentary and publishing rights, co-branded heritage programs with HBCUs and faith institutions, Black Wall Street education and tourism, commemorative products and, if the name does sunset, a stewardship or licensing arrangement for its continued historical use. Applied to the central modeled value of $3.97M, the 80/16/4 covenant splits as follows.
These are modeled covenant shares of a rated value, not projected cash flows. The point is structural. Under either deal path as currently described, none of the name's heritage value has a designated return lane, because the name has never been recorded as a property separate from the bank that uses it.
The gate is custody.
Whoever controls the bank after the vote controls the name, and can retire it.
The name and marks sit with the corporate entity. On an Optus close they pass to the acquirer, which has said the bank will take the Optus name about two years later. On a Triad path, Triad says the name would be kept. In neither case does the public record show a separate instrument, such as a heritage trust, a licensing covenant or an archive deed, that would protect the name's historical use independent of who controls the charter.
This record cannot see trademark filings, the merger agreement's treatment of marks and archives, or who holds the founding papers. Those three documents decide what is registrable. They are the first fields a Day-0 registration would capture.
- Deal-neutral. The constraint applies under any outcome. A retained name without a stewardship instrument is one future transaction away from the same question.
- Time-bound. The Optus timeline describes a runway of about two years between closing and the name change. That is the window in which a stewardship covenant is easiest to negotiate.
- Not a vote position. Nothing here is a recommendation on the October 20 vote or on either proposal.
A dormant heritage name is the most exposed kind.
Modeled exposure: $7.9M to $19.9M
Heritage names are prime material for synthetic reuse: generated "Black Wall Street" branding, AI-written histories that misattribute the founders, synthetic likenesses of Merrick, Spaulding or Wheeler in marketing, and look-alike financial products that borrow the lineage. A name in active use has a custodian watching it. A retired one does not. Under US trademark law, three consecutive years of non-use is prima facie evidence of abandonment, so a name that sunsets without a stewardship instrument can drift into the commons. Registration does not prevent that. It gives someone standing to answer it.
| Path | Name status | HLM | CUV | Trajectory |
|---|---|---|---|---|
| A · Optus closeAs agreed | Retired about 2 years after close | Holds if archived and stewarded | Toward 0 at sunset | Band holds as a heritage record only if a custodian instrument exists; otherwise HLM decays with dormancy |
| B · Triad pathAs proposed | Retained, Durham HQ | Holds | Holds at banking-only | Band stable; continuity alone adds no return lane |
| C · Either path + recordStewardship covenant | Registered, protected | Holds or rises with archive verified | Can rise via licensing | Upside toward 3.0× HLM and a broader surface |
What exists, who holds it, what is unverified.
| Element | Presumed holder | Verified | CPRS note |
|---|---|---|---|
| Name & wordmark"Mechanics and Farmers Bank," "M&F Bank" | M&F Bancorp / the bank | No | Core of the record; transfers with the charter |
| Founding archive1907 charter, minutes, ledgers | Unknown: bank, university or family collections | No | Decides the HLM multiplier; highest-priority field |
| Founders' names & likenessMerrick, Shepard, Spaulding, Wheeler and others | Historical; estates and families | No | Referenced, not held by the bank; attribution care required |
| Parrish Street associationBuilding, place identity | Building title not verified | No | Place lineage carries even where title does not |
| "Black Wall Street"Durham lineage | Descriptive commons | n/a | No one holds it; the record documents M&F's place in it |
| Customer & community recordsLoans, accounts | The bank; regulated | Excluded | Private financial data is never part of a cultural record |
Public record only, confidence 0.66.
This is a soft pass built on public sources, with no first-party data from M&F, Optus or Triad. Confidence sits at 0.66 because the history is well documented while the custody facts that matter most (marks, archive and the merger agreement's treatment of both) are not visible.
Age: 118 or 119118 counts from the 1908 opening; 119 from the 1907 charter.
Combined assetsAxios reports about $1 billion; The News & Observer about $1.3 billion. Neither is adopted.
Triad deadline and bid countOctober 21 comes from Triad's own release. Triad describes four proposals; M&F has not confirmed the count.
"51 percent control"A social media claim about bidder control has no primary source and is left out.
AttributionStatements of intent (Optus's naming plan, Triad's retention commitment, the board's reasoning) are attributed as reported, not independently verified. Jonathan Lee Kelly's claim that North Carolina would be left without an African American minority depository institution is his characterization.
No engagement impliedMADE CX has not been engaged by M&F Bancorp, Optus Financial or Triad Business Bank. This is independent analysis.
AI-written sourceHey Durham coverage is AI-generated and used only where it matches other reporting.
Formula. BCPV = CIS×0.30 + CCI×0.25 + LIP×0.20 + CUV×0.15 + HLM(raw)×0.10. CDC = 0.75 × 0.40 × sector multiplier. Index = BCPV × CDC. Base value by the value-unit method at $25,000 per index point, an analyst assumption for a regional heritage institution, disclosed and open to revision. TCPMV = base × HLM multiplier, presented as a band at ±(1 − confidence).
HLM form. Heritage appears in two forms: raw 94 at 10% weight inside BCPV, and a 2.8× multiplier applied once at the monetary stage. It is applied nowhere else.
Sector routing. The Framework lists no financial-services multiplier. This record routes at 3.0×, the Music & Entertainment level, as a neutral mid-range reference, and says so. Tech/AI (4.5×) would overstate a seven-branch community bank; Food/Beverage (2.5×) would understate the name's institutional weight.
Not an appraisal. Soft valuation, not an appraisal, not a registered record and not investment advice. It does not value M&F Bancorp, its shares or either proposal, and takes no position on the vote. Unattributed does not mean unpaid: noting that heritage value has no return lane does not assert that any party acted improperly. All company names are used descriptively.
Sources
- Axios Raleigh, rival bid, vote date, combined assets. October 16, 2026.
- The News & Observer, Optus terms, board rejection, "Party A," vote delay, Kelly comments. 2026.
- Hey Durham, Triad terms and community programs. AI-written; corroboration only.
- Wikipedia, "Mechanics and Farmers Bank", institutional history. Secondary; key dates to confirm against primary archives.
- Baradaran, The Color of Money, Harvard University Press, 2017.
- Winford, John Hervey Wheeler, Black Banking, and the Economic Struggle for Civil Rights, University Press of Kentucky, 2019.
- Butler (2012); Rogoff (2010); NCpedia, Williams (2006).
The name belongs on the record under any outcome.
The vote decides who controls the bank. It does not decide whether 118 years of lineage gets written down. That part is still open.
$MFBANK rates as a Tier 4 Heritage & Lineage property, with a modeled band of $2.6M to $5.3M driven almost entirely by lineage, not commerce. That is the kind of value an acquisition model has no line for and a sunset quietly ends. Whatever happens on October 20, the name's custodian faces the same choice: let the name ride with the charter, or record it as a heritage property with a steward, a protected scope and a Community Return lane back to Durham.
Record the name before anyone retires it.
Family estates, museums, archives and institutions like M&F hold names whose value no deal sheet itemizes. MADE CX builds a heritage-name record any custodian can open, under any outcome. It documents the property, protects its scope and routes a Community Return back to the place it came from.
Verify marks and archive custody and lift confidence above 0.80.
A name-and-archive instrument that survives any change of control.
A 4% lane to the place of origin on every future use of the name.